Getting married? Make sure you debunk your mortgage before tying the knot

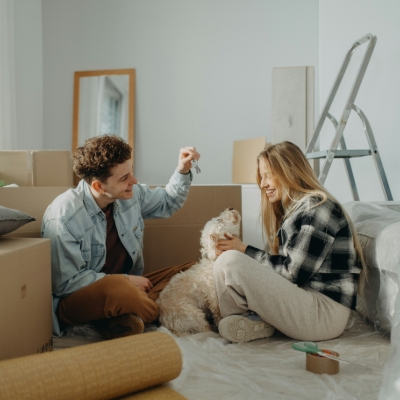
couple sitting on floor together in own home

First comes love, then comes marriage, then comes...... a mortgage! Yes, it may not sound that romantic, but owning your own home is high on the agenda for many nearlyweds-to-be.

While wedding plans may be top of the list, lots of couples (through no fault of their own) picture themselves settling into married life in the comfort of their perfect home without always considering the complexities that need some thought before achieving homeownership – such as being self-employed, having bad credit or being a single parent.

Applying for a mortgage can feel like information overload, and hard to separate the facts from fiction. There are many misconceptions around mortgage lending, which can be harmful as many people are left feeling insecure about their financial situation.

To help couples navigate the word of mortgages, Paul Coss, Co-Founder of Haysto, has debunked five common myths:

couple hugging in own home

1. You can't get a mortgage with a bad credit rating 
False. 
A poor credit score can make it more difficult when you're applying for a mortgage, but it doesn't make it impossible. Good lenders and brokers have seen it all and aren't judgemental. They should have mortgages specifically designed to help you both on the property ladder, even if your credit score isn't great. Whether or not you'll be able to get a mortgage will depend upon the severity of your credit issues, as well as how recent they were. But just because you have bad credit doesn't mean you can't get a mortgage. So that's one less thing to sweat over as you approach the big day!  

2. You can't get a mortgage if you're self-employed
False. 
Being self-employed can make getting a mortgage more difficult because a lot of mortgage lenders just don't have the experience of dealing with people who have a complex income. If you don't have a standard 9-5 job with three months' worth of payslips, lenders see you as a 'complex' case and sometimes just reject you because it's not easy for them to work out. That's obviously unfair. There are lots of specialist lenders who will consider your application. 

couple on sofa with ipad high-fiving

3. If you can't borrow enough, you'll need a big deposit 
False.
 If you're limited in how much you can borrow, maybe just because the property you both want is a little bit out of your budget, then you can consider putting down a bigger deposit. But if that isn't possible, there are government schemes that could help you get your mortgage without the need for a bigger deposit. For example, the Help to Buy equity loan which allows you to borrow between 15% and 40% of the value of the property. There's also the shared ownership scheme, which allows you both to buy a smaller share of the property while paying rent on the rest, meaning that you'll need a smaller deposit.  

4. A lower interest rate will mean a cheaper mortgage 
True.
But there are other factors that go into your monthly mortgage repayments, and therefore how expensive your mortgage is overall. For example, if you're on a tracker mortgage, this could rise at any time, which is why many opt for a fixed-rate mortgage. The agreed length of your mortgage will also have an impact on the amount that you pay each month and you'll also have fees to pay, which can be as much as £1,000 overall. Other things like how much your property is worth and if you're choosing to overpay also affect how much you'll pay for a mortgage.

5. Mortgage repayments cost more than rent 
False. 
Mortgage repayments often work out cheaper than rent. But it does depend on how much your rent is, where you live and how much your property is worth. Landlords generally charge more than their mortgage repayments to make a bit of profit, so often people find that when they move onto a mortgage from renting it works out cheaper. When you’re paying mortgage repayments, each payment is adding to your equity in the home, unlike rent, which goes straight to your landlord.

You may also be interested in

Speed up bridal prep with Coco & Eve's newest release

Speed up bridal prep with Coco & Eve's newest release

Lots of brides want that perfect glow on their big day and, in the run up to your wedding there's lots to be getting on with, so anything that can be made quicker and easier is a massive plus. Coco & Eve's newest release is perfect for a busy bride-to-be. Designed to eliminate the harsh scrubbing and over-exfoliating of the skin to remove leftover tan, giving you more time to focus on those wedding prep plans that need your time and attention. This scrub removes tan in just 60 seconds and leaves the skin prepped for a fresh application.
READ ARTICLE

Free Wills Month: Six things engaged and married couples should know about writing a will

Free Wills Month: Six things engaged and married couples should know about writing a will

Getting married is an exciting time, with plenty to plan and look forward to. While writing a will might not be top of the wedding to-do list, it's an important step in making sure your wishes are respected and your loved ones are protected if the unexpected happens. Free Wills Month gives people aged 55 and over the opportunity to write or update a simple will for free with a participating solicitor in selected locations across the UK. But you don't need to wait until you're 55 to make a will. Getting married, buying a home or starting a family are all good opportunities to think about how you'd like to protect your loved ones.

READ ARTICLE

Don't Leave Your Old Pensions Behind: A Wedding-Day Financial Checklist

Don't Leave Your Old Pensions Behind: A Wedding-Day Financial Checklist

With National Pension Tracing Day approaching on 25th October, millions of workers across the UK could have thousands of pounds in lost pension savings from previous jobs without even knowing it. As couples prepare for their big day and build a new life together, pensions are often the last thing on the wedding planning checklist, yet they are one of the most important pieces of your shared future. According to newly published research from the Pensions Policy Institute, there are an estimated 3 million lost pension pots across the UK, holding a staggering £18.7 billion. With the average UK worker changing employers 12 times over their career, losing track of old savings has become an easy trap to fall into.

READ ARTICLE

From ‘I do’ to ‘we own’: Five tips for newlyweds getting mortgage-ready

From ‘I do’ to ‘we own’: Five tips for newlyweds getting mortgage-ready

The wedding bells have rung, the honeymoon is over and married life is getting underway. For many newlyweds, the next exciting milestone is finding a place to call their own. Whether you've been renting, living separately or staying with family before tying the knot, buying your first home together is a big step. But just as planning the perfect wedding comes with its challenges, navigating the mortgage market and getting onto the property ladder as a newly married couple can bring its own set of hurdles. Tanya Elmaz, managing director of intermediary sales at Together, shares his five top tips for newlyweds looking to make their property dreams a reality.

READ ARTICLE

Follow Your Cheshire & Merseyside Wedding Magazine on Facebook

VISIT SITE

Follow Your Cheshire & Merseyside Wedding Magazine on Instagram

VISIT SITE

Follow Your Cheshire & Merseyside Wedding Magazine on YouTube

VISIT SITE

Subscribe to Your Cheshire & Merseyside Wedding Magazine for free

VISIT SITE